

















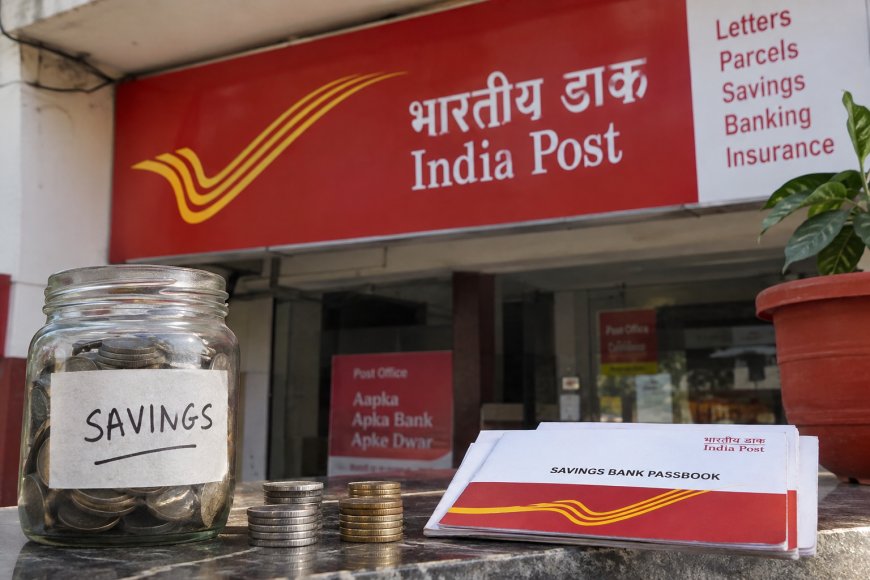
Post Office FD, RD & SCSS: Interest Rates, Limits & Returns
Post Office FD, RD and SCSS offer safe, predictable returns. Check interest rates, investment limits, SCSS income and the risks investors should know.
By Shefali Rana | BizGossips.in
Post Office savings schemes are back in the spotlight, offering something many investors value: predictable returns without the daily volatility of the stock market.
From a 365-day Post Office Fixed Deposit to Recurring Deposits and the Senior Citizens Savings Scheme (SCSS), these government-backed products can appeal to conservative investors.
But there is a question worth asking:
Are these schemes genuinely attractive—or are investors focusing too much on the headline interest rates?
365-Day Post Office FD: Safe, But Not a Jackpot
Post Office Time Deposits currently offer interest rates ranging from 6.90% to 7.50%, depending on the tenure.
The 365-day option can appeal to investors who want to park money for roughly a year without taking market risk.
The biggest attraction is stability. Unlike equity investments, the return is not directly linked to daily market movements.
But there is a trade-off.
“Safe” does not automatically mean “high return.”
A fixed-rate investment provides predictability, but investors also give up the possibility of higher returns that market-linked assets could potentially generate over the long term.
Post Office RD: Small Investments, Bigger Commitment
The Post Office Recurring Deposit is designed for investors who prefer to invest regularly rather than make a large one-time deposit.
That can make it useful for salaried individuals and small savers trying to develop financial discipline.
However, an RD isn't a shortcut to wealth.
The investor needs to make regular contributions and remain invested for the required period. Those “small investment, big corpus” headlines can therefore be somewhat misleading if they make wealth creation sound effortless.
The reality is simple: meaningful wealth through an RD requires time and consistency.
SCSS: Where the Numbers Look More Attractive
For eligible senior citizens, the Senior Citizens Savings Scheme (SCSS) stands out because of its relatively high interest rate.
According to the latest reported terms, SCSS offers 8.2% annual interest, with a maximum investment limit of ₹30 lakh.
At 8.2%, investing ₹30 lakh would generate approximately ₹2.46 lakh in annual interest.
Because SCSS interest is paid quarterly, that works out to:
-
₹61,500 every quarter
-
Approximately ₹20,500 per month when averaged
But that ₹20,500 is not a monthly payout. The actual interest is received quarterly.
SCSS generally caters to individuals aged 60 years and above, with certain provisions for eligible retirees below 60. The initial tenure is five years, with an extension option available under the scheme rules.
Safe Doesn't Mean Suitable for Everyone
This is where investors need to look beyond the interest rate.
SCSS interest is taxable, while small-savings rates can be revised by the government. Liquidity and lock-in requirements also differ between products.
Therefore, the “best” scheme depends on the investor's objective.
For eligible retirees seeking predictable income, SCSS may be attractive. For shorter-term fixed-income needs, a Post Office FD could be more relevant. For disciplined periodic saving, an RD may make sense.
BizGossips Take
Post Office schemes deserve attention because they combine government backing and predictable returns.
But investors should be careful about turning that safety into an automatic “best investment” label.
The real comparison isn't simply 6.9% versus 8.2%.
It is about taxes, liquidity, tenure, inflation, and financial goals.
A high interest rate can look great on paper. But the right investment is ultimately the one that fits the investor—not necessarily the one with the most attractive headline.
Safe can be valuable. But safe and suitable are two different things.
Disclaimer
This article is based on publicly available information and is intended for informational and editorial purposes only. Interest rates, eligibility, taxation, withdrawal conditions, and scheme rules may change. Readers should verify the latest terms through official sources before investing. This article does not constitute investment, financial or tax advice.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0